 Mirmi
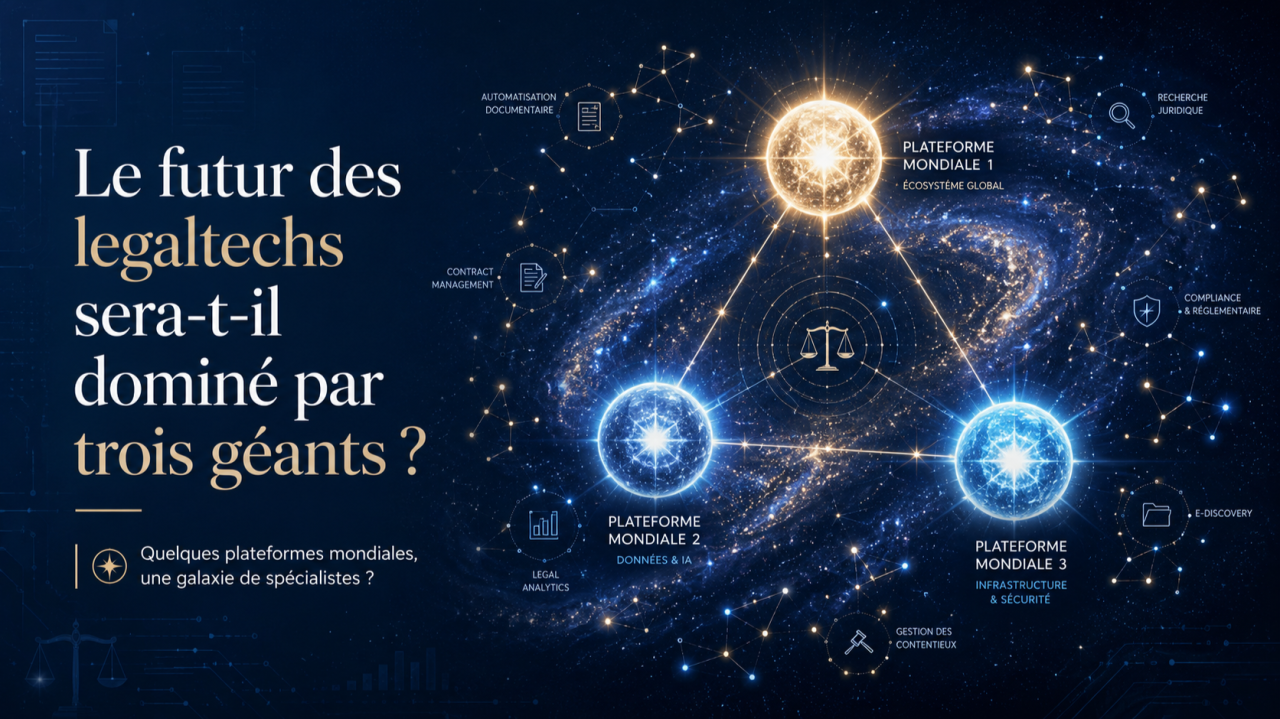
Legal AI has entered a period of extreme capital concentration.
Harvey reached an $11 billion valuation after raising another $200 million. Legora raised $550 million at a $5.55 billion valuation and later announced that it had surpassed $100 million in annual recurring revenue less than eighteen months after its commercial launch. Legal startups globally reportedly raised $2.1 billion during the first half of 2026.
The apparent conclusion is straightforward: the market will eventually belong to a handful of global platforms able to invest more heavily in products, security, distribution and AI models.
In the Les Échos article published on 17 July, one law firm partner predicted that the market would consolidate around three major players. Legora’s CEO went further, suggesting that 90% of AI companies could disappear.
Consolidation is highly likely.
Total domination is far less certain.
The giants have substantial advantages
A large platform can spread its investments across thousands of customers, deploy commercial teams in multiple countries and meet the security requirements of large enterprises more easily.
It can also become the lawyer’s daily entry point: research, drafting, analysis, collaboration and agents brought together in one interface.
The more that interface is used, the harder it becomes to replace.
For generic activities—summarising a document, conducting an initial search, producing a draft or comparing two versions—a few platforms could therefore capture a significant share of the market.
But “law” is not one market
Litigation, patents, employment law, contracting, compliance and law-firm management do not rely on the same data, processes or risk thresholds.
Business Insider’s selection of legal startups to watch in 2026 illustrates that fragmentation. Some simulate judges and juries; others search internal knowledge, manage patents, capture billable time, route legal requests or rebuild the law-firm model itself.
This does not look like a market converging towards one universal product.
It looks like an industry creating several technology layers.
The most likely outcome: a few platforms surrounded by many specialists
Three to five companies may control the general-purpose interface and core infrastructure.
Around them, however, specialised solutions will continue to go much deeper into a particular practice, jurisdiction, workflow or data category.
Some will be acquired. Others will become partners. A few will build global leadership positions in narrow markets.
Legal departments will therefore probably not choose one winner, but an architecture:
- a general platform for common use cases;
- specialist tools for complex processes;
- systems of record to retain data;
- shared governance to control decisions.
The real question is not who will survive
It is which part of the value chain each company will control.
For a legal department, the risk is not limited to selecting a small vendor that might disappear.
It also includes placing all its data, workflows and working interface in the hands of a provider that becomes almost impossible to replace.
The future of legal tech will probably be more concentrated.
But it will not necessarily be monopolised.
A few giants may control access to legal work. They are unlikely to control all of its depth.
This publication is based on an analysis first shared by Mirmi on LinkedIn.
View on LinkedIn